The global electronic warfare (EW) market is entering a period of significant technological development as defence forces increase investments in electromagnetic spectrum operations, advanced sensing, electronic attack, countermeasures and spectrum awareness.
According to Cervicorn Consulting, the global electronic warfare market was valued at USD 26.45 billion in 2025 and is projected to reach approximately USD 51.97 billion by 2035, expanding at a CAGR of 7% between 2026 and 2035. The growth is being supported by defence modernisation programmes, rising investment in advanced military electronics and the increasing importance of electromagnetic spectrum superiority.
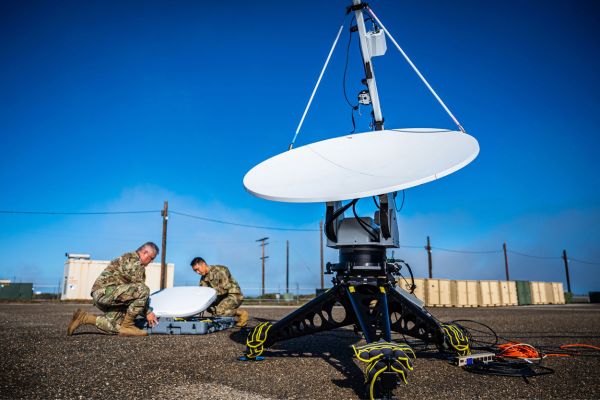
Electronic warfare has evolved well beyond conventional signal jamming. Modern EW architectures increasingly combine receivers, signal processing, electronic support measures, electronic attack, electronic protection, artificial intelligence and networked sensors to detect and respond to rapidly changing electromagnetic threats.
AI Is Changing Electronic Warfare
One of the most important developments in the EW sector is the integration of artificial intelligence and machine learning.
Modern military environments can generate enormous volumes of electromagnetic signals. Conventional systems can face challenges when identifying, classifying and prioritising signals in increasingly complex environments.
AI-enabled EW systems can support faster signal analysis, automated threat identification and adaptive responses. Cognitive electronic warfare takes this development further by enabling systems to adjust their response based on changing electromagnetic conditions.
The growing adoption of software-defined and upgradeable architectures is also allowing defence organisations to introduce new capabilities through software and processing improvements rather than relying entirely on hardware replacement.
Counter-UAS Becomes an Important EW Application
The rapid proliferation of unmanned aerial systems is creating additional requirements for electronic warfare and counter-UAS technologies.
EW systems can contribute to counter-UAS operations through capabilities such as detection, identification, signal monitoring, jamming and other electronic countermeasures. Integration with radar, electro-optical systems, sensors and command-and-control technologies can provide a broader approach to identifying and responding to unmanned threats.
Cervicorn Consulting identifies counter-UAS operations as one of the fastest-growing application areas in the electronic warfare market, reflecting increasing defence attention toward drone-related threats.
The development of counter-UAS technologies is also creating opportunities for companies working across RF systems, sensors, AI, signal processing and autonomous platforms.
From Platform-Specific EW to Multi-Domain Operations
Electronic warfare is increasingly being integrated across air, land, maritime, space and other connected operational environments.
Airborne platforms remain an important area for EW deployment. Fighter aircraft, helicopters and dedicated electronic warfare aircraft require capabilities for threat warning, signal detection, electronic attack and platform protection.
At the same time, naval and land-based systems are expanding their EW capabilities, while space-based systems are receiving greater attention for electromagnetic intelligence, surveillance and signal detection.
This transition is encouraging defence suppliers to develop EW architectures that can exchange information across multiple platforms and operational domains.
Directed Energy and Advanced Countermeasures
Directed-energy technologies are another area attracting attention within the electronic warfare ecosystem.
Defence organisations are exploring directed-energy systems for applications involving rapidly developing threats, including counter-UAS missions. Advances in power electronics, RF technologies, antennas, signal processing and thermal management are contributing to the development of increasingly sophisticated systems.
Cervicorn Consulting identifies directed-energy weapons as a high-growth equipment category within the broader electronic warfare market.
However, the deployment of advanced EW and directed-energy technologies requires substantial investment in research, development, testing, integration and specialised engineering capabilities.
North America Remains a Major EW Market
North America continues to represent a significant portion of global electronic warfare demand. Cervicorn Consulting estimates that North America accounted for 38% of global EW market revenue in 2025, supported by defence spending, military modernisation and established EW technology capabilities.
The region is also home to several major defence technology companies developing electronic attack, electronic protection, radar warning, signal intelligence and spectrum-management solutions.
Meanwhile, Asia Pacific is expected to record the fastest growth over the forecast period, supported by defence modernisation programmes, increasing investments in advanced military electronics and growing demand for surveillance, electronic attack and counter-UAS technologies.
India Strengthens Focus on Indigenous EW Technologies
India is also placing greater emphasis on domestic defence electronics and indigenous technology development.
Government programmes supporting domestic defence manufacturing, research and development and technology-led procurement are creating opportunities for Indian companies across radar, communications, electronic warfare, surveillance and countermeasure technologies.
Recent developments highlighted by Cervicorn Consulting include defence procurement activity involving ground-based multi-purpose jammers and other EW-related systems, as well as work on high-power microwave technologies for naval applications.
The broader Indian defence-electronics ecosystem is also moving toward more advanced architectures involving AI, unmanned systems, secure communications and sensor fusion. Recent industry developments reported by TimesTech similarly illustrate the growing convergence of electronic warfare, counter-UAS, AI and defence electronics.
The Road Ahead for Electronic Warfare
The next phase of electronic warfare is likely to be shaped by the convergence of AI, software-defined architectures, autonomous systems, advanced RF technologies, directed energy, sensor fusion and multi-domain operations.
Rather than operating as standalone systems, EW capabilities are increasingly becoming part of broader digital defence architectures. This shift is placing greater emphasis on interoperability, real-time data processing, rapid software upgrades and the ability to operate in contested electromagnetic environments.
As defence forces modernise their platforms and respond to increasingly complex electronic and unmanned threats, demand for sophisticated EW technologies is expected to remain an important part of the global defence-electronics landscape.